Full diagnostic. Growth Opportunity Diagnostic and Recommendations for Fortune Brands Water Innovations and Connected Products. Public-record research pass and top-up pass, October 2026.
A sample Radar from the public record
Growth Opportunity Diagnostic and Recommendations for Fortune Brands Water Innovations and Connected Products, Sawhney Enterprises, October 2026, public-record research pass with a top-up pass. Arena and opportunity scores are illustrative judgments from the public record. Connected revenue by product is not disclosed. Contributions are the report's risk-adjusted totals spread across the lead bets in proportion to their composite.
Context
This report diagnoses where the Water Innovations business of Fortune Brands Innovations, together with its connected-products program (Moen Flo leak protection, SpringWell filtration and the Yale and August residential smart locks), can grow, and recommends which growth opportunities it should pursue, which it should watch, and which it should refuse. It applies the Growth Radar, a diagnostic instrument that asks two questions of a growth agenda: whether the unit's ambition can be reached from its core trajectory, and if not, where the winnable opportunity lies to close the distance. The framework scans eight growth arenas in four families, scores each arena on whether the space is real, whether the prize is worth taking, and whether the unit can win, and then generates a broad set of net-new opportunities and screens each one with the same three questions, multiplied so that a weak answer on any one vetoes the bet. The method is set out in Sawhney, M. (2026), The Growth Radar and the Growth Canvas: A Playbook for Finding and Evaluating Growth Opportunities, SSRN Working Paper, forthcoming.
Executive Summary
Fortune Brands' Water business is a USD 2.4 billion, 23 percent margin franchise that has shrunk for two years, lost share in retail and e-commerce in 2025, and spent 2026 fixing its own service levels while a new chief executive, the third leadership arrangement of the year, resets priorities. Beside it sits a connected-products program, Moen Flo and the Yale smart locks, that reached a run rate approaching USD 300 million at the end of 2025, grew Flo by more than half in a year, and carries a public ambition of USD 1 billion of connected sales by 2030. Held together as one unit of about USD 2.6 billion, the ambition for 2030 is roughly USD 3.7 billion: a Water core that outgrows a flat repair-and-remodel market by a point or two, plus the connected billion. The core on its current path reaches USD 2.8 to 3.2 billion. The gap, meaning the sales the unit must find beyond what its present business will deliver on its own, is USD 0.5 to 0.85 billion of 2030 sales, and USD 0.3 to 0.47 billion on a 2028 horizon.
The 40 net-new opportunities this scan surfaced do not close that gap. After discounting each for the chance it fails, they are worth about USD 0.18 to 0.46 billion of 2030 sales, a little under half of the gap at the midpoint, and even the top of that range falls short of the bottom of the gap. A second research pass on rivals lowered the estimate: Moen and Delta already sell kitchen filtration at the tap, and the leading multifamily platform is installing new units more slowly than the first pass assumed. The honest reading is that the USD 1 billion connected target is reachable only through the insurance channel, where a British rival with 26 carriers already runs the model Moen needs, and that the unit's binding problem in 2026 is execution in the core.
The search should concentrate in three of the eight arenas. New Occasions and Jobs scores highest because water damage has become an insurance job (22.6 percent of homeowner losses) and water quality a regulatory job (the 2024 PFAS drinking-water rule), and Flo's shutoff valve, its claims evidence and five million registered app users are assets no fixture rival holds. Adjacent Categories ties for second because filtration, water-heater protection and parcel security share the Moen and Yale brand permission and the home-center shelf. New Segments is the third focus because insurers, multifamily owners and rental operators buy protection in fleets, and the Yale Pro 2 lock and the first top-10 builder win show the assets travel.
One opportunity reaches the pursue-now band: an insurer-funded Flo program, in which carriers buy and deploy devices for selected policyholders, scores 80 out of 125 on the screen described in this report. Every carrier program Moen and its rival Phyn have announced asks the policyholder to pay for the device, so the carrier-funded model remains open to the device that shuts the water off. A Moen kitchen faucet with certified PFAS filtration and a cartridge consumable follows at 60, and multifamily water protection bundled with the Yale Pro 2 lock at 48. Of the 40 candidates, 32 survived, eight were vetoed (seven because the unit cannot win them, among them a Yale hotel lock the license does not permit, a smart-home hub, and a company-owned plumbing service; one because there is no profit pool), and 16 announced initiatives were set aside as already in motion.
Leadership must make one decision. Either fund the insurer-funded program and the filtration faucet at a scale that builds a recurring second engine before 2028, while the core is repaired, or restate the connected ambition as USD 0.6 to 0.75 billion by 2030 and let Flo and Yale grow as adjacencies. A third route, buying the insurer-channel capability the organic portfolio lacks, is open if the first contracts stall. The verdict rests on the insurer-funded program and the PFAS faucet; if the insurer-funded program fails, coverage falls to about a third of the gap.
1 The business in brief
Fortune Brands Innovations is a three-segment parent, and the Growth Radar is built for one business with one value chain, so the first task is to scope the unit. The Water segment sells faucets, showers, luxury bath and filtration under Moen, ROHL, Riobel, Victoria and Albert, Perrin and Rowe, Aqualisa, Shaws, Emtek, Schaub and SpringWell, and it is "increasingly investing in and developing digital products and 'smart' home capabilities" (FBIN 2026d, p. 4). The connected program crosses segments: Flo and connected water sit in Water, while the Yale and August residential smart locks and Master Lock's connected lockout products sit in Security (FBIN 2026b). From January 2025 one executive, David Barry, ran "the security business unit and our growing digital business" as President, Security and Connected Products; he is now chief operating officer (FBIN 2026e; FBIN 2026k). This report scopes the Water segment plus the Yale and August residential connected locks, because they share the Moen Smart Water and Yale Access apps, the home-center and e-commerce shelf, the builder and multifamily buyers and the insurer and smart-home partners. Master Lock's mechanical and industrial lines, SentrySafe and the Outdoors segment are left out.
The core is large, profitable and shrinking. Water sold USD 2,447.6 million in 2025, down 4.6 percent, with operating income of USD 570.5 million before charges, a 23.3 percent margin; the decline came "primarily due to sales volume decreases in China of USD 87.8 million" (FBIN 2026a; FBIN 2026d, p. 28). Excluding China, 2025 sales fell about 1 percent, mainly in wholesale volume (FBIN 2026b). The first half of 2026 was worse: Water sales fell 0.3 percent in the first quarter and 6.5 percent in the second, to USD 605.0 million, with price up low single digits and volume down high single digits (FBIN 2026g; FBIN 2026l). Management attributed about half of the second-quarter decline to share losses carried over from early 2025 and half to its own service failures, which cost about 2.5 points of sales after a new planning system "did not deliver the required levels of inventory" (FBIN 2026m). The segment's reported margin of 29.5 percent in that quarter included a USD 66 million tariff refund; without it the margin fell about 700 basis points, and the chief operating officer said "the next couple quarters probably represent more of a trough for Water margins" (FBIN 2026m). In May 2026 the interim chief executive conceded that "we've had overreliance on gross price, and it's cost us some share positions," while a plumbing peer grew about 7 percent in local currency against Water's 1.5 percent outside China (FBIN 2026h; Fool 2026). In the second quarter Masco's plumbing sales fell 3 percent in local currency after it redeployed part of its tariff refund into customer programs recorded against net sales, and its chief executive said Masco continues "to gain share across almost every channel" (Masco 2026a; Masco 2026b). The market is weak for every maker: LIXIL's Americas revenue fell 7 percent in the quarter to June 2025, which it attributed to renovation demand and an ERP transition (LIXIL 2025).
The customers and channels concentrate. Lowe's and The Home Depot each took 11 percent of 2025 sales, home centers together about 26 percent, the top ten customers 52 percent, and the two home centers about 21 percent of Water sales (FBIN 2026d, p. 4). New construction is about a quarter of sales and tied to housing completions (FBIN 2025a). About 16 percent of sales were international, Water about 22 percent; by destination the United States took USD 3,742.1 million, Canada USD 344.1 million, China USD 147.2 million and other countries USD 229.8 million (FBIN 2026d, p. 24). The luxury portfolio behaves differently from Moen: House of Rohl grew low double digits at point of sale in late 2025 and outperformed Moen through 2026, and management calls its demand "a whole lot less price sensitive" (FBIN 2025a; FBIN 2026b; FBIN 2026m).
The connected program is the growth story. Digital sales exceeded USD 200 million in 2024 and were "approaching that USD 300 million annualized" by the end of 2025, split with "a good balance between both security and water"; the chief executive said in October 2025 he was "absolutely convicted about the USD 1 billion by 2030" (FBIN 2025e; FBIN 2025a). Flo grew more than 50 percent in 2025, driven by e-commerce and wholesale; the Yale Smart Lock with Matter grew more than 50 percent sequentially in the fourth quarter; Yale signed 12 integration partnerships in 2025; and the company counts "over 5 million registered users across our digital platforms" (FBIN 2026b; FBIN 2025a). The 2026 leadership has neither restated nor withdrawn the billion-dollar target. It calls connected "less than 10 percent" of the portfolio and declines to guide it, describes Flo and Yale as "adjacencies that have become core," and calls Yale "one of the smaller businesses" with "good potential" (FBIN 2026b; FBIN 2026m; FBIN 2026o). In his first earnings call the new chief executive said "we've already made the investments necessary in our adjacency in the connected space" and set the priorities as "better service, better products, and a simpler, more customer-focused organization" (FBIN 2026m).
The right-to-win inventory is concrete and uneven. The strongest asset is the Flo Smart Water Monitor and Shutoff: a valve that shuts the main, a daily micro-leak test that detects a drop a minute, and claims evidence from a 2020 LexisNexis study of 2,306 homes showing a 96 percent reduction in water-damage claim events (Moen 2025a; Moen 2026). On that evidence Moen launched a Leak Protection subscription in 2025 whose three-year plan covers up to USD 5,000 of deductible, an Insurance Partner Program open to carriers of any size, and a Liberty Mutual partnership (Moen 2025a; Moen 2025b; FBIN 2026b). In 2026 Moen added policyholder programs with PEMCO and Stand Insurance, and Frontdoor installs Flo for program customers in 14 states (Moen 2026b; Coverager 2026; Frontdoor 2025). The second asset is brand permission: Moen is, on the company's survey work, "the most trusted brand of faucets" in North America, and the 2024 SpringWell acquisition (USD 105.6 million) added whole-home filtration, softeners and reverse osmosis sold direct (FBIN 2025e; FBIN 2026u); Moen also sells filter-ready kitchen faucets with under-sink filters (Moen 2026c). The third is distribution: the home-center shelf, plumbing wholesale, 67 net builder wins in 2025, a two-decade exclusive with Meritage Homes, Yale's first top-10 homebuilder award and the Yale Pro 2 multifamily lock (FBIN 2026b; Moen 2024; FBIN 2026h). The fourth is the smart-home position: Yale Assure Lock 2 named best smart lock by CNET and The Spruce, the Matter lock designed for Google Home, and a Yale Access app that now manages Matter connections across platforms (FBIN 2025a; FBIN 2026s). The fifth is a North American supply chain with 14 United States plants, four in Mexico and China sourcing falling toward 5 percent of cost of goods by late 2027 (FBIN 2026d, p. 18; FBIN 2026h). What the unit does not hold is also clear: a proven recurring-revenue operation (the subscription is a year old), a national installation network (installation is offered "where available"), carrier contracts at scale (every Moen carrier program read asks the policyholder to pay for the device), and any connected revenue disclosure by product. Flo installs, subscriber counts and Yale's revenue are not public, and the Win scores below assume the claims evidence and the user base are as described.
The ambition is public but split between two managements. The connected target of USD 1 billion by 2030 was stated in October 2025 (FBIN 2025a). For the core, the recurring commitment is to outperform the end market: Water point of sale grew low single digits against a market down low single digits in late 2025, and the February 2026 guidance called for Water sales flat to up 2 percent in a market down low single digits, before the May cut to down low single digits for the company (FBIN 2026b; FBIN 2026c; FBIN 2026g). Three assumptions convert that into a gap, labeled illustrative. The unit's 2025 base is about USD 2.6 billion: Water of USD 2,448 million plus roughly USD 150 million of Yale and August connected sales, derived from the "good balance" statement about a USD 300 million run rate. The 2030 ambition is USD 3.7 billion: the Water core excluding connected water (about USD 2.3 billion) growing 3 percent a year, which is a point or two above the 0.5 to 2.1 percent remodeling growth the Joint Center projects into 2027 (JCHS 2026), plus USD 1 billion of connected sales. The core trajectory is the Water core falling about 4.5 percent in 2026 and then growing 1 to 2.5 percent a year, plus connected sales growing 12 to 20 percent a year from USD 0.3 billion, the band consistent with Flo decelerating as its base grows and Yale growing slowly. On those assumptions the core reaches USD 2.8 to 3.2 billion in 2030 and the gap is USD 0.5 to 0.85 billion (equation 5 in Appendix B); on a 2028 horizon the core reaches USD 2.65 to 2.85 billion against an ambition of USD 3.1 billion, a gap of USD 0.3 to 0.47 billion. About half of the gap in either year is the distance between the connected billion and a 12 to 20 percent path, and the other half is the share the core must win back in a flat market.
2 Where the unit can grow
The Radar scores each arena on three lenses, each an integer from 1 to 5: whether the growth spaces in the arena are real and durable (Real), whether the prize is deep and material against the gap (Worth), and whether the unit holds named, transferable assets there (Win). The radius of each spoke is the geometric mean of the three (equation 1), so an arena with a large prize the unit cannot win is pulled toward the center. Scores are absolute and illustrative. The area of the polygon is a diagnostic of winnable opportunity; it is not a budget allocation.
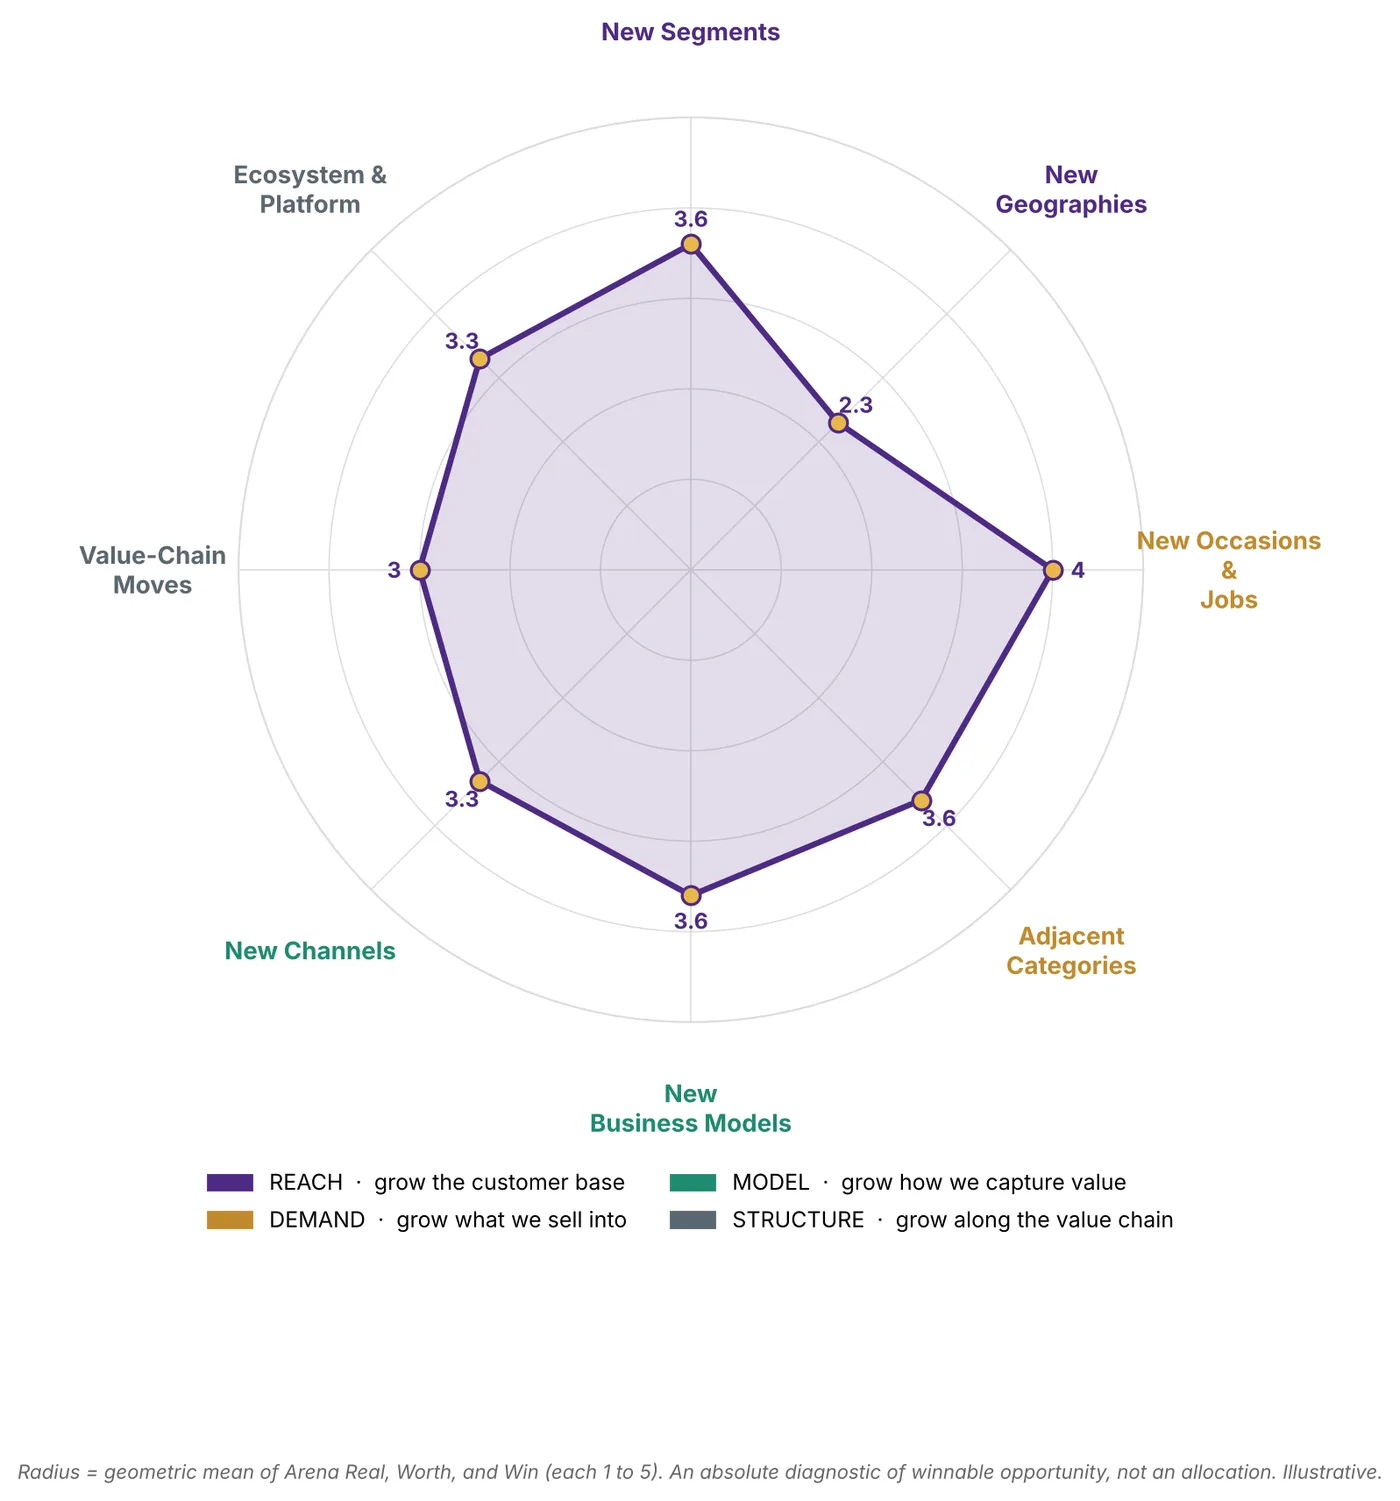
Table 1. The eight arenas: Real, Worth, and Win lenses and the resulting radius.
| Arena | Family | Real | Worth | Win | Radius |
|---|---|---|---|---|---|
| New Occasions and Jobs | Demand | 4 | 4 | 4 | 4.0 |
| Adjacent Categories | Demand | 4 | 3 | 4 | 3.6 |
| New Segments | Reach | 4 | 3 | 4 | 3.6 |
| New Business Models | Model | 4 | 4 | 3 | 3.6 |
| New Channels | Model | 4 | 3 | 3 | 3.3 |
| Ecosystem and Platform | Structure | 4 | 3 | 3 | 3.3 |
| Value-Chain Moves | Structure | 3 | 3 | 3 | 3.0 |
| New Geographies | Reach | 3 | 2 | 2 | 2.3 |
New Occasions and Jobs (4.0) is the only balanced 4 on the radar. Water damage and freezing were 22.6 percent of homeowner insurance losses in 2023, at an average severity of USD 15,400, and insurers pay more than USD 15 billion a year in water claims (III 2025; Moen 2025a); the PFAS drinking-water rule puts water quality on the household agenda through 2031 (EPA 2026). Flo's valve, its claims evidence and the five-million-user app carry these jobs. Win is 4 rather than 5 because Phyn, LeakBot and Resideo sell the same job and LeakBot already contracts with carriers (Ondo 2026a). Phyn's programs with Nationwide and Amica offer a 15 percent device discount, the same customer-pays form as Moen's, and Kohler sells H2Wise monitoring built by Phyn (Nationwide 2024; Coverager 2024; Phyn 2021). Resideo, which separated its ADI distribution business on 3 August 2026, now runs its USD 695 million-a-quarter products segment as a standalone home-products company (Resideo 2026).
Adjacent Categories (3.6) scores 4 on Win because filtration, water heaters and parcel security share the Moen and Yale brand permission, SpringWell's product line and the home-center and builder shelf. Worth binds at 3: each pool is moderate against the gap, and filtration is contested by Culligan, Pentair and Brita-class cartridge makers and by Delta, whose Clarifi under-sink system with a beverage faucet is certified to NSF standards 42, 53 and 401 and reduces PFOA and PFOS (Delta 2026).
New Segments (3.6) scores 4 on Real on the deep evidence: commercial is now the largest Security channel, Yale Pro 2 and the first top-10 builder win opened multifamily and production builders, and carriers now buy leak devices in fleets, with Nationwide ordering 35,000 more LeakBots for the second half of 2026 (FBIN 2026h; Ondo 2026a). Worth binds at 3 because the institutional pools are mid-sized. The lock rivals are moving: Allegion's Americas residential business grew high single digits organically in the second quarter of 2026 against 3.8 percent for FBIN's Security segment, ASSA ABLOY reported small growth in North American residential, and Kwikset launched a Matter lock at USD 189, the price of Yale's (Allegion 2026; SSN 2026; ASSA ABLOY 2026; FBIN 2026l; Kwikset 2026; Yale 2025). Win holds at 4 because it rests on the multifamily, builder and insurer assets as well as the lock.
New Business Models (3.6) leads on Worth. A premium-funded, outcome-priced leak subscription is the largest single prize on the radar. Win binds at 3: the Leak Protection subscription launched only in late 2025, the unit has never contracted on claims outcomes, and LeakBot's recurring revenue is already 83 percent of its sales with validated control-group data (FBIN 2026b; Ondo 2026a).
New Channels (3.3) is real: restoration contractors, home-warranty firms, plumbing wholesale and utilities can all carry connected water. Win falls to 3 on management's own account of 2025 share losses in retail and e-commerce and 2026 service-constrained volume, while Masco claims share gains across almost every channel (FBIN 2026h; FBIN 2026m; Masco 2026b).
Ecosystem and Platform (3.3) has real counterparts in Matter, Google Home, insurers and builders. Worth and Win bind at 3: the home platform belongs to Apple, Google, Amazon and Samsung, platform revenue is indirect, and Yale is a small business inside a USD 4.5 billion parent.
Value-Chain Moves (3.0) and New Geographies (2.3) are the weakest spokes. Installed-price offers and monitoring services are credible but thin, and the plumbers who install Moen are the channel any service move must not displace. Outside North America the unit has 16 percent of sales, a China business that lost USD 87.8 million in 2025, and thin channels; a British rival owns the insurer relationships in the one European market where Flo has a service footprint (FBIN 2026d, p. 24; Ondo 2026a).
3 The three arenas to focus
3.1 New Occasions and Jobs
This arena lights up because two outside forces have turned water from a fixture purchase into a protection job. The first is the insurance economy. Water and freezing claims run at 1.5 per 100 house-years, a severity of USD 15,400, and nearly a quarter of homeowner losses; one home in six files a water claim over a decade (III 2025; Moen 2025a). Carriers have moved from discounts to funding devices: Nationwide ships a monitoring system free and ties a policy discount to activation within 55 days, and LeakBot's United States device count more than doubled to 57,408 in the year to March 2026 and reached about 66,000 by June; Selective, which began offering LeakBot in February 2024, extended it to 15 states in March 2026 (Nationwide 2026; Ondo 2026a; Ondo 2024; Ondo 2026b). The second force is regulation. The 2024 PFAS rule sets a 4 parts-per-trillion limit for PFOA and PFOS, requires monitoring by 2027 and compliance by 2029, with a May 2026 proposal to extend to 2031; it is expected to reach about 100 million people (EPA 2026). Each exceedance notice is a reason for a household to buy filtration.
The prize is recurring and attached to an installed base. Flo grew more than 50 percent in 2025 and management expects the subscription to open both the consumer and the insurance channels, because insurance savings can offset the install cost from the first day (FBIN 2025a; FBIN 2026b). The right-to-win headroom is the valve: LeakBot detects and notifies; Flo detects and shuts the main. Rivals that shut the main (Phyn, Resideo) do not have Moen's shelf or its plumber network.
The moves this arena points to are new jobs for the same device and app: freeze and vacancy protection for second homes, water-quality monitoring across Flo and SpringWell, a package sold at the moment of a claim, and a host bundle for short-term rentals. The trap is an occasion real for a few power users and not a population; drought budgeting is scored down for that reason.
3.2 Adjacent Categories
Three near-categories sit on the unit's existing permission. Filtration is the largest: SpringWell sells whole-home filters, softeners and reverse osmosis direct, and its August 2026 campaign reframed filtration as peace of mind (FBIN 2026u). Moen's faucet position lets it carry filtration to the kitchen tap, where the PFAS rule creates demand the household can act on without a plumber. That shelf is occupied: Moen already sells filter-ready kitchen faucets with under-sink filters, Delta sells a certified under-sink system with its own faucet, and Elkay markets a two-in-one faucet with a filter certified to NSF 53 and 401 that reduces PFOA and PFOS (Moen 2026c; Delta 2026; Elkay 2026). The open space is a faucet whose certified PFAS cartridge the household replaces on subscription. Water heaters are the second: they are among the most common sources of interior water loss, and a leak pan sensor wired to Flo's valve is a small engineering step. Parcel security is the third: Yale's access platform and multifamily relationships transfer to the package-theft job that Amazon Key and Parcel Pending sell today.
The right-to-win headroom is brand permission plus shelf. The 10-K names InSinkErator among Water's competitors, a reminder that the kitchen adjacency is already contested by appliance makers (FBIN 2026d, p. 4). Arena Win is 4 because Moen's brand and the home-center shelf transfer; Worth is 3 because each pool is moderate and the filtration consumable is where the margin lives.
The trap is the classic false adjacency. Home energy management and a Yale camera line both look next door and both fail Win: one belongs to another industry's value chain and the other to the video platforms. Both are vetoed below.
3.3 New Segments
The buyers growing fastest are institutions, and the evidence that the unit can sell to them arrived in 2026. Commercial became the largest channel in Security and supports price increases because demand is less elastic (FBIN 2026h). Yale Pro 2 launched for multifamily in February 2026 and management is prioritizing multifamily volume over promotion (FBIN 2026h; FBIN 2026m). A top-10 homebuilder awarded Yale business for the first time, and Moen holds an exclusive with Meritage Homes (FBIN 2026h; Moen 2024). Carriers buy in fleets: LeakBot has 26 carriers and 11 United States partners in 26 states (Ondo 2026a). SmartRent, which serves 15 of the top 20 multifamily owners, shows the owner-operator buyer exists at scale, and its pace shows the limit: it deployed 18,857 new units in the second quarter of 2026, down 10 percent, on an installed base of about 930,000 (SmartRent 2026; SmartRent 2026b). Owners report that leak detectors cut about a quarter of water-related maintenance tickets (Parks 2026).
New Segments was chosen as the third focus ahead of New Business Models, which also scores 3.6, on the first tie-break rule, right-to-win headroom: New Segments holds Win 4 on the Yale Pro 2, builder and insurer assets, while New Business Models holds Win 3 because the recurring-revenue operation is a year old. On the second rule, the share of the gap an arena can close, the two are close, since the insurer-funded program and the premium-funded subscription reach the same policyholders. New Business Models remains strong and holds the premium-funded subscription (48) and the filter consumable (48) in the pursue-next band, and the report treats the insurer-funded program and the premium-funded subscription as one pair in Section 6.
The trap is a segment that wants a different product. Multifamily owners want riser-level detection, a portfolio dashboard and integration with their property software, none of which the consumer Flo and Yale apps provide today. The scored bets assume that dashboard is built, and the Win score falls if it is not.
4 The opportunity set
The scan generated 40 net-new opportunities, grouped below by arena, with the three focus arenas first. Each carries a boldness tag: Extend is a small step from the core, Stretch a real reach with familiar muscles, Step out a new model or buyer, and Transform a different game.
4.1 New Occasions and Jobs
1. Freeze and vacancy protection service for second homes and seasonal owners. Flo's freeze alerts and remote shutoff packaged as a seasonal service that satisfies insurers' vacancy clauses. Stretch. The device and the five-million-user app are the asset; Phyn and LeakBot sell the same job.
2. Whole-home water quality monitoring across Flo and SpringWell. Flow, pressure, filter life and utility PFAS reports on one app. Stretch. SpringWell's filtration line and Moen's app are named assets; in-home contaminant sensing is unproven.
3. Drought and tiered-rate water budgeting for Western households. Fixture-level usage against utility tiers, with the Smart Sprinkler Controller. Stretch. The pool is small against the gap.
4. Aging-in-place bath and entry bundle for seniors and caregivers. Anti-scald and touchless fixtures, Flo auto-shutoff and Yale caregiver codes. Stretch. The buyer is fragmented and the bundle needs a care-services partner.
5. Short-term-rental host package. Keyless turnover through Yale, leak and overuse alerts through Flo, sold through Airbnb and Vrbo host programs. Stretch. Both devices already serve hosts individually; the bundle and the channel are new.
6. Water-damage never-again package sold at the point of claim. The homeowner who has just filed a USD 12,500 claim buys Flo through the adjuster or the restoration firm. Extend. The LexisNexis evidence and the insurer program carry it.
4.2 Adjacent Categories
7. Moen kitchen faucet with integrated certified PFAS filtration and cartridge consumables. A faucet that filters at the tap, with a replaceable certified cartridge sold on subscription. Stretch. The PFAS rule is a structural shift; Moen's filter-ready faucets, SpringWell's know-how and the shelf are named assets; Delta's certified Clarifi system and the filter makers contest it.
8. Water-heater failure protection. A tank-leak pan sensor and shutoff integrated with Flo. Stretch. Flo's valve and app extend directly; the water-heater makers can add the same feature.
9. Light-commercial touchless fixtures with usage analytics for facilities. Moen Commercial fixtures with Flo's sensing for restrooms. Stretch. Sloan, Zurn and Kohler hold the specification channel.
10. Yale connected parcel locker and mailbox. For homes and multifamily lobbies. Step out. Amazon Key, Parcel Pending and Luxer One already sell it.
11. Home energy monitoring and EV-charger control under the Moen app. Transform. Another industry's value chain; no transferable asset beyond the app.
12. Yale video doorbell and home camera line. Transform. The camera and the video cloud belong to Ring, Google and Arlo.
4.3 New Segments
13. Insurer-funded Flo program. Carriers buy and deploy Flo for selected policyholders, as Nationwide does with LeakBot, with Moen handling fulfillment, installation and monitoring. Step out. Flo's valve and claims evidence are stronger than the detection-only rivals; the carrier contracting record is weaker.
14. Multifamily water protection bundled with Yale Pro 2. Unit and riser leak detection with shutoff, sold to owner-operators with a portfolio dashboard. Stretch. Yale Pro 2 opens the door; SmartRent, Phyn Dashboard and Sensor Industries contest it.
15. Senior-living and assisted-living facility package. Access, anti-scald fixtures and leak protection in one specification. Step out. The operator is a new buyer.
16. Build-to-rent and single-family rental operators. Fleet protection with a portfolio dashboard for institutional landlords. Step out. They already specify Moen; the dashboard is the missing piece.
17. Small-business access bundle through security dealers. Yale doors plus Master Lock Commercial Connected Access. Stretch. Commercial is the largest Security channel; the Yale residential license limits the door hardware.
18. Value-tier Moen line for first-time buyers against private-label imports. Extend. Moen's 2025 campaign names the threat; a value tier risks trading the brand down.
19. Yale hospitality locks for hotels. Step out. The Yale residential license held by FBIN does not cover hospitality, which remains with ASSA ABLOY.
4.4 New Business Models
20. Premium-funded Leak Protection. The carrier pays the subscription per policy and shares avoided claims with Moen. Step out. The largest prize on the radar; the subscription is a year old and LeakBot already contracts on outcomes.
21. Builder-warranty leak protection. Monitoring included in the new-home warranty for a per-home fee. Step out. Builders control the bundle and new construction is falling.
22. Home water-risk analytics licensed to insurers and reinsurers. Underwriting signals from five million users' leak events. Step out. The data asset is unique among fixture makers; the buyer and the privacy terms are unbuilt.
23. Auto-replenished filter cartridge subscription. Across SpringWell and Moen filtration. Extend. Consumables on an installed base; Brita, Culligan and Amazon contest it.
24. Fixture leasing and rent-to-own for luxury bath. Transform. No profit pool.
4.5 New Channels
25. SpringWell Pro filtration line through plumbing wholesale and installing plumbers. Stretch. SpringWell sells direct; Moen's wholesale position takes it to the installed channel.
26. Restoration-contractor channel. Flo installed during water-damage repairs by Servpro and BELFOR franchisees. Stretch. The channel must be built from zero.
27. Home-warranty and home-services platforms embedding Flo. Frontdoor-class warranty firms and Angi-class platforms. Step out. Frontdoor already installs Flo for Moen in 14 states; the platforms run competitive bids.
28. Water-utility conservation programs offering Flo rebates. Step out. Slow, municipal and shared with Flume and Phyn.
29. Moen Pro replenishment app for plumbers and property managers. Predictive replacement of fixtures from installed-base data. Extend. Ferguson's own tools compete for the plumber's screen.
30. Direct-to-consumer subscription storefront undercutting home-center pricing. Step out. Pits Moen against the customers who carry 21 percent of Water sales.
4.6 Value-Chain Moves
31. Installed-price Flo offer through a certified Moen installer network. Stretch. Installation is the adoption barrier; Frontdoor covers 14 states today, the rest of the network must be contracted, and installation margins are thin.
32. Monitored shutoff and plumber-dispatch concierge service. Step out. A recurring fee with new operations and liability.
33. Residential water utility metering and operations. Transform. Regulated operations the unit has never run.
34. Company-owned plumbing and restoration service business. Transform. The plumbers who install Moen would become competitors.
4.7 Ecosystem and Platform
35. Home water-risk event API for insurers, utilities and smart-home platforms with revenue share. Stretch. A coordination position only a device maker with scale can hold; the first participants need a reason to pay.
36. Pre-installed Matter home package for production builders. Moen, Yale and partner devices as one package. Stretch. Resideo, Schneider and the builders' own programs contest the orchestrator role.
37. Consumer smart-home hub and operating platform. Transform. The hub layer belongs to Apple, Google, Amazon and Samsung.
4.8 New Geographies
38. Canadian insurer leak-protection rollout with Riobel and Moen Canada. Stretch. Canada is 8 percent of parent sales and freeze claims are frequent; LeakBot and the carriers' own programs contest it.
39. United Kingdom Flo launch through Aqualisa and Perrin and Rowe. Step out. LeakBot's home market, with Admiral, Direct Line and Hiscox contracted.
40. European premium plumbing entry through acquisition. Step out. Continental channels are thin and management favors organic investment.
4.9 Already in motion (excluded)
Sixteen initiatives were screened out because the company has announced or disclosed them as underway. They are the Leak Protection subscription and the FloProtect plan; the Insurance Partner Program, the Liberty Mutual partnership, the Amica, Farmers, PEMCO and Stand programs and the expansion of national insurance partnerships; Flo's growth through wholesale and e-commerce with installation where available, including Frontdoor installation in 14 states; the Yale Smart Lock with Matter and the Yale Access Matter-management update; the 12 Yale integration partnerships of 2025 and the 2026 slate; Yale Pro 2 and the prioritization of multifamily volume; the first top-10 builder award, the Meritage exclusive and the 67 net builder wins; cross-brand bundling with two e-commerce platforms; the SpringWell acquisition, site refresh and campaign; the SwivelControl faucet, the Retrofit Wand, the filter-ready kitchen faucets and the "Must Be a Moen" campaign; the House of Rohl and Emtek collections and surgical luxury pricing; the Master Lock Elite padlock, packaging refresh, cLOTO and Commercial Connected Access test beds; the Aqualisa smart showers and the Smart Water Network devices; the service recovery and planning rebuild in Water; the USD 70 million cost program and the China sourcing reduction; and the Fiberon review and portfolio review of sub-segments (FBIN 2025a; FBIN 2026b; FBIN 2026h; FBIN 2026m; FBIN 2026s; FBIN 2026u; Moen 2025a; Moen 2025b; Moen 2024b; Moen 2024c; Moen 2026b; Moen 2026c; Coverager 2026; Frontdoor 2025). Public sources reveal what is announced, so un-announced internal initiatives cannot be screened until a run against internal materials.
5 Which opportunities to pursue
Each opportunity is scored from 1 to 5 on Real, Worth and Win, and the three scores are multiplied (equation 2), so a composite runs from 8 to 125; any score of 1 vetoes the bet (equation 4). Scores are illustrative judgments. Verdicts follow the composite: 64 and above is pursue now, 30 to 63 pursue next, 15 to 29 watch, and below 15 re-scope.
Table 2. Live opportunities ranked by composite score (illustrative).
| \# | Opportunity | Arena | Boldness | Real | Worth | Win | Score | Verdict |
|---|---|---|---|---|---|---|---|---|
| 13 | Insurer-funded Flo program: carriers buy and deploy devices for selected policyholders | Segments | Step out | 5 | 4 | 4 | 80 | Pursue now |
| 7 | Moen kitchen faucet with integrated certified PFAS filtration and cartridge consumables | Adjacent | Stretch | 5 | 3 | 4 | 60 | Pursue next |
| 1 | Freeze and vacancy protection service for second homes and seasonal owners | Occasions | Stretch | 4 | 3 | 4 | 48 | Pursue next |
| 2 | Whole-home water quality monitoring across Flo and SpringWell | Occasions | Stretch | 4 | 3 | 4 | 48 | Pursue next |
| 5 | Short-term-rental host package: keyless turnover, leak and overuse alerts | Occasions | Stretch | 4 | 3 | 4 | 48 | Pursue next |
| 6 | Water-damage never-again package sold at the point of claim | Occasions | Extend | 4 | 3 | 4 | 48 | Pursue next |
| 8 | Water-heater failure protection: tank-leak pan sensor and shutoff integrated with Flo | Adjacent | Stretch | 4 | 3 | 4 | 48 | Pursue next |
| 14 | Multifamily water protection: unit and riser leak detection bundled with Yale Pro 2 | Segments | Stretch | 4 | 3 | 4 | 48 | Pursue next |
| 16 | Build-to-rent and single-family rental operators: fleet protection with a portfolio dashboard | Segments | Step out | 4 | 3 | 4 | 48 | Pursue next |
| 17 | Small-business access bundle through security dealers: Yale doors plus Master Lock Commercial Connected Access | Segments | Stretch | 4 | 3 | 4 | 48 | Pursue next |
| 23 | Auto-replenished filter cartridge subscription across SpringWell and Moen filtration | Bus. Models | Extend | 4 | 3 | 4 | 48 | Pursue next |
| 25 | SpringWell Pro filtration line through plumbing wholesale and installing plumbers | Channels | Stretch | 4 | 3 | 4 | 48 | Pursue next |
| 27 | Home-warranty and home-services platforms embedding Flo | Channels | Step out | 4 | 3 | 4 | 48 | Pursue next |
| 31 | Installed-price Flo offer through a certified Moen installer network | Value-Chain | Stretch | 4 | 3 | 4 | 48 | Pursue next |
| 20 | Premium-funded Leak Protection: the carrier pays the subscription per policy and shares avoided claims | Bus. Models | Step out | 4 | 4 | 3 | 48 | Pursue next |
| 29 | Moen Pro replenishment app for plumbers and property managers | Channels | Extend | 3 | 3 | 4 | 36 | Pursue next |
| 4 | Aging-in-place bath and entry bundle for seniors and caregivers | Occasions | Stretch | 4 | 3 | 3 | 36 | Pursue next |
| 9 | Light-commercial touchless fixtures with usage analytics for facilities | Adjacent | Stretch | 4 | 3 | 3 | 36 | Pursue next |
| 10 | Yale connected parcel locker and mailbox for homes and multifamily | Adjacent | Step out | 4 | 3 | 3 | 36 | Pursue next |
| 15 | Senior-living and assisted-living facility package | Segments | Step out | 4 | 3 | 3 | 36 | Pursue next |
| 22 | Home water-risk analytics licensed to insurers and reinsurers for underwriting | Bus. Models | Step out | 4 | 3 | 3 | 36 | Pursue next |
| 26 | Restoration-contractor channel: Flo installed during water-damage repairs | Channels | Stretch | 4 | 3 | 3 | 36 | Pursue next |
| 35 | Home water-risk event API for insurers, utilities and smart-home platforms with revenue share | Ecosystem | Stretch | 4 | 3 | 3 | 36 | Pursue next |
| 36 | Pre-installed Matter home package for production builders: Moen, Yale and partner devices | Ecosystem | Stretch | 4 | 3 | 3 | 36 | Pursue next |
| 38 | Canadian insurer leak-protection rollout with Riobel and Moen Canada | Geographies | Stretch | 4 | 3 | 3 | 36 | Pursue next |
| 21 | Builder-warranty leak protection: monitoring included in the new-home warranty for a per-home fee | Bus. Models | Step out | 3 | 3 | 3 | 27 | Watch |
| 28 | Water-utility conservation and leak programs offering Flo rebates | Channels | Step out | 3 | 3 | 3 | 27 | Watch |
| 32 | Monitored shutoff and plumber-dispatch concierge service | Value-Chain | Step out | 3 | 3 | 3 | 27 | Watch |
| 3 | Drought and tiered-rate water budgeting for Western households | Occasions | Stretch | 3 | 2 | 4 | 24 | Watch |
| 18 | Value-tier Moen line for first-time buyers against private-label imports | Segments | Extend | 3 | 2 | 3 | 18 | Watch |
| 39 | United Kingdom Flo launch through Aqualisa and Perrin and Rowe relationships | Geographies | Step out | 3 | 3 | 2 | 18 | Watch |
| 40 | European premium plumbing entry through acquisition | Geographies | Step out | 3 | 3 | 2 | 18 | Watch |
Table 3. Opportunities parked on a veto.
| \# | Opportunity | Arena | Failing ring | Why it fails |
|---|---|---|---|---|
| 11 | Home energy monitoring and EV-charger control under the Moen app | Adjacent | Win | Different-industry archetype: electrical load control is another value chain with Schneider, Emporia and the utilities already in it; no transferable asset beyond the app. |
| 12 | Yale video doorbell and home camera line | Adjacent | Win | Own-the-device archetype: the camera and video cloud belong to Ring, Google and Arlo; the winnable move is the Matter lock endpoint those platforms control. |
| 19 | Yale hospitality locks for hotels | Segments | Win | Win veto: FBIN holds the Yale and August residential business in North America; hospitality and commercial Yale remain with ASSA ABLOY, so there is no permission to enter. |
| 24 | Fixture leasing and rent-to-own for luxury bath | Bus. Models | Worth | Worth veto: no profit pool; luxury buyers and designers pay cash and the financing margin belongs to Affirm-class lenders. |
| 30 | Direct-to-consumer subscription storefront undercutting home-center pricing | Channels | Win | Channel-conflict veto: Lowe's and Home Depot are 11 percent of sales each and about 21 percent of Water; a price-led direct channel pits Moen against the customers who carry the core. |
| 33 | Residential water utility metering and operations | Value-Chain | Win | Different-industry archetype: regulated utility operations the unit has never run. |
| 34 | Company-owned plumbing and restoration service business | Value-Chain | Win | Vertical-into-service and channel-conflict archetypes: the plumbers who install Moen would become competitors. |
| 37 | Consumer smart-home hub and operating platform | Ecosystem | Win | Own-the-device archetype: the hub layer belongs to Apple, Google, Amazon and Samsung; supply the Matter endpoint instead. |
The top of the list survives the false-adjacency check. Opportunity 13 earns Win 4 from Flo's shutoff valve, the LexisNexis evidence and the carrier relationships with Liberty Mutual, PEMCO and Stand; opportunity 7 from Moen's filter-ready faucets, SpringWell's filtration line and the home-center shelf; opportunity 14 from Yale Pro 2 and the multifamily volumes management is already prioritizing. Opportunities 7 and 14 dropped from pursue now to pursue next in the second research pass, because Moen's own line and Delta already serve filtration at the tap and SmartRent's deployment pace points to a smaller multifamily prize (Appendix A). None of the live bets earned a Win 5, because every connected asset is contested by a rival that is further along in one dimension: LeakBot in carrier contracting, Phyn in the multi-property dashboard, the filter makers in cartridges. The Win scores should be revisited with internal data on Flo installs, subscriber counts, Yale revenue and the terms of the Yale license.
6 Does the portfolio close the gap
The insurer-funded program and the two bets that led the first pass were sized from unit economics, with every assumption labeled illustrative and open to challenge.
The insurer-funded Flo program (opportunity 13) is sized from the carrier upward. LeakBot, the only rival running this model at scale, grew to about 167,000 active devices by June 2026 with 26 carriers, and one carrier alone intends to order 35,000 devices in a half-year (Ondo 2026a). If five to eight United States carriers fund Flo for their high-value and high-loss policyholders, deploying 150,000 to 300,000 devices a year by 2030 at roughly USD 400 per device and installation to the carrier, device sales are USD 60 to 120 million a year, and a monitoring fee of about USD 60 a year on a cumulative base of 0.6 to 1.0 million devices adds USD 36 to 60 million. Allowing for the share of these homes that would otherwise have bought Flo at retail, the net-new 2030 prize is USD 0.10 to 0.15 billion.
The PFAS filtration faucet (opportunity 7) is sized from the affected household upward. The rule reaches about 100 million people, and exceedance notices begin with the 2027 monitoring deadline (EPA 2026). If 2 to 3 million households install a filtering faucet or under-sink unit by 2030 in response, at USD 250 to 350, and Moen captures 25 to 35 percent in line with its faucet position, annual device sales in 2030 are USD 60 to 120 million and cartridges on an installed base of about 0.75 million units at USD 60 a year add about USD 45 million. Moen already sells filter-ready kitchen faucets with under-sink filters, and Delta sells a certified system with its own faucet, so part of this demand would reach Moen's existing line and is counted in the core (Moen 2026c; Delta 2026). Net of that line and of SpringWell's direct sales, the net-new prize is USD 0.05 to 0.10 billion.
Multifamily water protection (opportunity 14) is sized from the unit upward. Institutional owners hold millions of apartments and SmartRent alone serves 15 of the top 20 owners (SmartRent 2026). SmartRent deployed 18,857 new units in the second quarter of 2026 and holds about 930,000 (SmartRent 2026b). If owners equip 150,000 to 300,000 units a year by 2030 with leak detection and shutoff at about USD 400 a unit, category sales are USD 60 to 120 million a year; because Yale Pro 2 is already in motion and the lock revenue is in the core, the incremental Flo attachment and dashboard subscription are worth USD 0.04 to 0.08 billion.
The three bets therefore contribute USD 0.19 to 0.33 billion of net-new 2030 sales before any discount for failure. The other 22 pursue-next bets could add USD 0.2 to 0.9 billion if every one succeeded, a directional sum of USD 10 to 40 million each. Discounting the three sized bets at a 60 percent chance of success and the other pursue-next bets at 30 percent gives USD 0.18 to 0.46 billion (equation 6), against a gap of USD 0.5 to 0.85 billion: about a fifth of the gap when the gap sits at the top of its range, nine-tenths when it sits at the bottom, and a little under half at the midpoint. With every bet at the top of its range the net-new portfolio still stops short of the bottom of the gap, so closing it also requires the core to recover to the 2.5 percent path and connected sales to hold 20 percent a year without the new bets. No plan should rest on that combination.
The verdict rests on two bets. The insurer-funded program and the premium-funded subscription (opportunity 20) are one pair aimed at the same carriers, and the PFAS faucet is the only lead bet that draws on the core's fixture franchise. Together they carry about 40 percent of the risk-adjusted total. Both depend on things the unit has not yet proven: a sale to carriers as customers with service-level and claims-sharing terms, and a consumable business with cartridge logistics Moen has never run.
Four conditions would make even this partial coverage fail. LeakBot or Phyn may close the carrier channel first: LeakBot's United States device count doubled in a year, it holds 11 United States partners in 26 states, and carriers that have standardized on a detection-only device will resist a second supplier (Ondo 2026a). The core may absorb the investment: management has said the next quarters are a trough for Water margins, the USD 70 million cost program is sequenced against 2027 reinvestment, and a chief executive seven weeks into the role has promised specifics "over the next quarter or two" and has said the connected investments are already made (FBIN 2026m; FBIN 2026o). The PFAS rule may soften: the May 2026 proposal extends compliance to 2031 and rescinds four of the six limits, which slows the exceedance notices that drive household demand (EPA 2026). And the multifamily bet may stall on the dashboard the consumer apps lack.
The portfolio does not close the gap on its own. The organic bets can lift the unit's growth by about one to two points a year by 2030 and carry connected sales to roughly USD 0.7 to 0.85 billion, short of the USD 1 billion target. The remaining distance has three answers: fund the carrier pair and the filtration faucet beyond pilot scale in 2027, while the core is repaired, so that a recurring second engine is running when the housing market turns; restate the connected ambition as USD 0.6 to 0.75 billion by 2030 and let Flo and Yale grow as adjacencies, which is where the new management's language already points; or buy the carrier-channel capability, which in practice means an insurer-distribution business of the LeakBot type or a filtration pro brand with an installer network. The recommendation is the first, with the third held as the response if no carrier contract of 25,000 devices or more is signed by the end of 2027.
The shape of the portfolio is healthy in reach and thin at the top. Thirty-six of the 40 candidates are Stretch, Step out or Transform, and six are Transform bets, so the scan did not merely defend the core. Only one bet reaches pursue now. The binding problem is scale: the lead bet is worth about a sixth of the gap and the next two about a tenth each, and the unit's attention in 2026 is on service levels and share recovery in a business twenty times their size.
7 What the unit will not pursue
Eight opportunities are refused. The Yale hotel lock fails Win because FBIN acquired the Yale and August residential business, and hospitality and commercial Yale remain with ASSA ABLOY; the license is the boundary. The consumer smart-home hub and the Yale camera line fail Win on the own-the-device archetype: the hub and the video cloud belong to Apple, Google, Amazon, Samsung, Ring and Arlo, and the winnable version is the Matter lock and valve endpoint those platforms control, which Yale already supplies. Home energy management and residential water utility operations fail Win as moves into other industries' value chains. A company-owned plumbing and restoration service fails Win on both the vertical-into-service and the channel-conflict archetypes, because the plumbers who install Moen and Flo would become competitors; the winnable version is opportunity 31, a certified installer network. The direct-to-consumer storefront that undercuts home-center pricing fails Win on channel conflict with the two customers who carry 21 percent of Water sales. Fixture leasing fails Worth: luxury buyers pay cash and the financing margin belongs to lenders.
The 16 initiatives listed as already in motion are also left out of the scored set. They are sound moves, and the diagnostic treats them as proof of the assets that make the new bets winnable, above all the Leak Protection subscription, the insurer partner program, Yale Pro 2 and the SpringWell acquisition.
8 What happens next
Five bets should move into the next stage, which scopes each one onto a Growth Canvas with an owner, a budget and a date for a decision:
- The insurer-funded Flo program (13) and the premium-funded subscription (20), run as one carrier proposition: which carrier signs first, at what device and monitoring price, and whether the contract shares avoided claims or pays a flat fee.
- The PFAS filtration faucet (7) with the cartridge subscription (23): how a certified cartridge sets the product apart from Moen's filter-ready faucets and Delta's Clarifi system, which certification the cartridge needs, what the home centers will give in shelf space, and whether SpringWell or a partner makes the cartridge.
- Multifamily water protection (14): whether to build the portfolio dashboard or integrate with SmartRent-class platforms, and which owner pilots first.
- The never-again package at the point of claim (6) and the restoration-contractor channel (26), run as one experiment with two test cells (adjuster referral and contractor install) and a control group, to learn whether the moment of loss converts at a rate that justifies a channel.
- The SpringWell Pro line through plumbing wholesale (25): whether the installing plumber will carry a direct-to-consumer brand and at what margin.
Four gaps in the public record limit the scores and should be closed with internal data: Flo installs and subscriber counts, Yale and August revenue and the terms of the Yale license, SpringWell's revenue and installer base, and the carrier pipeline behind the insurer partner program. The radar should be run again in April 2027, after the new chief executive has stated the strategy he promised, the Water service recovery has two quarters of data, and the first full year of the Leak Protection subscription can be read.
Appendix A. Method Note and Source Ledger
The diagnostic scanned eight growth arenas, scored each on Real, Worth and Win, and took the geometric mean as the arena radius. It generated 40 net-new opportunities, screened out 16 announced initiatives, scored each opportunity on the same three rings, multiplied the scores, and vetoed any opportunity with a ring at 1. All scores and prize ranges are illustrative judgments grounded in public evidence as of 12 October 2026. Fortune Brands' third-quarter 2026 results, due in late October, were not available. Connected-product revenue is not disclosed by product or segment; the split used here derives from management's statements that the run rate approached USD 300 million with a balance between water and security. Entries marked [snippet] were verified from a search result or a partial page rather than a fetched document. A second research pass on 12 October 2026 read the documents the first pass could not reach: Masco's and Resideo's second-quarter 2026 results and Masco's call transcript, Allegion's and ASSA ABLOY's second-quarter 2026 reports, LIXIL's first-quarter results for the year to March 2026, the Yale Smart Lock with Matter launch release, SmartRent's second-quarter 2026 results, and the 2024 to 2026 carrier programs of Moen and Phyn. Kohler's current H2Wise page, Fortune Brands' connected revenue by product and any 2026 analyst note on the connected ambition remain unread or undisclosed.
The deep research pass moved several scores from the earlier outside-in read of this unit. New Segments moved from 3.3 to 3.6 because commercial is now the largest Security channel, Yale Pro 2 and the first top-10 builder win opened institutional buyers, and carriers now buy leak devices in fleets (Real 3 to 4). New Channels moved from 3.6 to 3.3 because management conceded share losses in retail and e-commerce in May 2026 and service-constrained volume in August (Win 4 to 3). Ecosystem and Platform moved from 3.6 to 3.3 because platform revenue is indirect and the new chief executive describes Yale as one of the smaller businesses (Worth 4 to 3). New Geographies moved from 2.9 to 2.3 because China sales fell USD 87.8 million in 2025 and international sales are 16 percent of the parent (Worth 3 to 2). New Occasions and Jobs held at 4, 4, 4; Adjacent Categories at 4, 3, 4; New Business Models at 4, 4, 3; Value-Chain Moves at 3, 3, 3. The earlier read left the wedge unsized; this report quantifies it at USD 0.5 to 0.85 billion for 2030. Of the earlier read's scored bets, the insurer-embedded subscription was re-scored to Win 3 on the LeakBot evidence, the whole-home water intelligence and small-business bundle bets were carried at their scores, the builder water-as-a-service bet was carried as a watch, and the three vetoes (smart-home hub, water utility operations, European acquisition as a thin geographic move) held, and the European entry is kept live as a watch.
The second research pass re-tested every Win score of 4 or 5 against what rivals are doing and every Real and Worth score against the new market evidence. No arena score moved. Masco's claim of share gains in almost every channel and its redeployment of tariff refunds into customer programs confirm New Channels at Win 3. Allegion's high-single-digit residential growth and Kwikset's USD 189 Matter lock press on the Yale assets, yet New Segments holds Win 4 because it also rests on the multifamily, builder and insurer assets. Delta's certified filtration confirms Adjacent Categories at Worth 3, and Phyn's discount-based carrier programs leave New Occasions and Jobs at Win 4. Four opportunity scores moved. Opportunity 7, the PFAS filtration faucet, moved from Worth 4 to Worth 3 (80 to 60, pursue now to pursue next) because Moen already sells filter-ready kitchen faucets and Delta sells a certified system, so the net-new prize narrows to USD 0.05 to 0.10 billion (Moen 2026c; Delta 2026). Opportunity 14, multifamily water protection, moved from Worth 4 to Worth 3 (64 to 48) because SmartRent's 18,857 new units in a quarter, down 10 percent, do not support 300,000 or more protected units a year by 2030; its prize narrows to USD 0.04 to 0.08 billion (SmartRent 2026b). Opportunities 27 and 31, the home-warranty channel and the installed-price offer, moved from Win 3 to Win 4 (36 to 48) because Frontdoor already installs Flo for Moen in 14 states (Frontdoor 2025). Opportunity 13 held at 80: every carrier program read, Moen's and Phyn's alike, is a discount or preferred price the policyholder pays, so the carrier-funded model remains open (Moen 2026b; Coverager 2026; Nationwide 2024; Coverager 2024). Risk-adjusted coverage fell from USD 0.24 to 0.55 billion to USD 0.18 to 0.46 billion, the central reading from about 55 to about 47 percent of the gap, and the pursue-now set from three bets to one.
Investor and financial filings. FBIN 2026a: Fourth-quarter and full-year 2025 results release, 12 February 2026, ir.fbin.com. FBIN 2026b: Q4 2025 earnings call transcript, 12 February 2026, ir.fbin.com. FBIN 2026c: Q4 2025 earnings presentation, 12 February 2026, ir.fbin.com. FBIN 2026d: Annual Report on Form 10-K for fiscal 2025, filed February 2026, materials.proxyvote.com (business and MD&A sections read; notes section not available in the fetched text). FBIN 2026e: 2026 Proxy Statement, March 2026, ir.fbin.com. FBIN 2026g: First-quarter 2026 results release, 7 May 2026, ir.fbin.com. FBIN 2026h: Q1 2026 earnings call transcript, 7 May 2026, ir.fbin.com. FBIN 2026l: Second-quarter 2026 results release, 4 August 2026, ir.fbin.com. FBIN 2026m: Q2 2026 earnings call transcript, 4 August 2026, ir.fbin.com. FBIN 2026n: Q2 2026 earnings presentation, 4 August 2026, ir.fbin.com. FBIN 2026o: Deutsche Bank Chicago Industrials Summit transcript, 11 August 2026, ir.fbin.com. FBIN 2025a: Q3 2025 earnings call transcript, 30 October 2025, ir.fbin.com. FBIN 2025b: Third-quarter 2025 results release, 30 October 2025, ir.fbin.com. FBIN 2025c: Second-quarter 2025 results release, 31 July 2025, ir.fbin.com. FBIN 2025e: 2024 Annual Report (FUTURE NOW), March 2025, ir.fbin.com. Investing.com 2026: Fortune Brands Q4 2025 presentation summary, 12 February 2026, investing.com [secondary]. Fool 2026: "Here's How Masco Shocked the Market This Week" (Masco Q1 2026 results), 24 April 2026, fool.com [secondary]. Masco 2026a: "Masco Corporation Reports Second Quarter 2026 Results," 29 July 2026, masco.com investor site. Masco 2026b: Q2 2026 earnings call transcript, 29 July 2026, masco.com investor site. Resideo 2026: "Resideo Announces Record Second Quarter 2026 Financial Results; Initiates Standalone 2026 Outlook," 12 August 2026, investor.resideo.com. Allegion 2026: "Allegion Reports Q2 2026 Financial Results," 23 July 2026, allegion.com. SSN 2026: "Allegion Sees Double-Digit Growth in Q2," Security Systems News, 23 July 2026, securitysystemsnews.com [secondary]. ASSA ABLOY 2026: Quarterly Report Q2 2026, 17 July 2026, release via inderes.se. LIXIL 2025: Results for the first quarter of the year ending March 2026, 31 July 2025, newsroom.lixil.com. Ondo 2026a: Ondo InsurTech plc final results for the year to 31 March 2026, RNS, 30 July 2026, ondoplc.com.
Customer and demand signals. III 2025: Facts and statistics, homeowners and renters insurance (2023 ISO claims data; NAIC premium), iii.org. JCHS 2026: "Remodeling Spending Poised for Further Slowdown," Leading Indicator of Remodeling Activity, 23 July 2026, jchs.harvard.edu. Moen 2025a: "Any Size Insurance Agency or Carrier Can Now Partner with Moen," 14 April 2025, prnewswire.com (claims statistics, LexisNexis 2020 study). Moen 2026: Flo Smart Water Monitor and Shutoff page (bundle, FloProtect plan, device data), shop.moen.com, read October 2026. SmartRent 2026: Investor overview (serves 15 of the top 20 multifamily owners), investors.smartrent.com, read October 2026 [snippet]. SmartRent 2026b: "SmartRent Reports Second Quarter 2026 Financial Results," 5 August 2026, streetinsider.com (Business Wire). Parks 2026: "New Research: Smart Tech Retrofits Upgrade to Strategic Necessity for Multifamily Owners" (Parks Associates and RealPage), Mann Report, 26 February 2026, mannpublications.com [secondary].
IP and capability. Moen 2020: "Moen Takes Majority Stake in Smart Water Start-Up Flo Technologies," 8 July 2020, prnewswire.com [snippet]. Moen 2021: "Moen Launches Industry-First Smart Water Network," 11 January 2021, prnewswire.com [snippet]. Moen 2022: "Moen Launches Smart Faucet," 4 January 2022, prnewswire.com [snippet]. Moen 2023: "Moen Smart Sprinkler Controller," 4 January 2023, prnewswire.com [snippet]. FBIN 2026s: "Yale Simplifies Smart Home Experience for Matter-Enabled Smart Locks," 4 August 2026, fbin.com. FBIN 2026t: "Yale and August Enhance User Experience," 27 May 2026, fbin.com. FBIN 2026r: Connected Products page, fbin.com, read October 2026. Yale 2025: "Yale Smart Lock for Google Home Now Available" (USD 189.99, Matter over Thread), 24 June 2025, shopyalehome.com. Moen 2026c: Moen Weymouth FS73004 pull-down filter kitchen faucet listing, thegranitegroup.com, and F9940 replacement filter listing, pacesupply.com, read October 2026 [snippet].
Data assets. FBIN 2025a (five million registered users). Moen 2026 (device data on leak notification within 30 days).
Brand and distribution. Moen 2024: "Moen Expands Two-Decade-Long Partnership with Meritage Homes as the Exclusive Plumbing Partner," 30 September 2024, prnewswire.com. Moen 2025b: "Moen Partners with Liberty Mutual Insurance," 10 April 2025, prnewswire.com. Moen 2025c: "Moen Raises the Alarm on the Health Risks of Cheap, Off-brand Faucets," 16 May 2025, prnewswire.com [snippet]. FBIN 2026u: "SpringWell Launches 'Know Your Water Is Just Water' Campaign," 14 August 2026, fbin.com. FBIN 2025d: "Fortune Brands Expands Key Leadership Team Roles," 17 July 2025, ir.fbin.com. Moen 2026b: "PEMCO Mutual Insurance Partners with Moen to Help Homeowners Prevent Costly Water Damage," 18 June 2026, GlobeNewswire via wboc.com. Coverager 2026: "Stand and Moen Launch Smart Water Leak Program with Insurance Discounts," 8 July 2026, coverager.com [secondary]. Frontdoor 2025: "Frontdoor and Moen Expand Relationship to 6 Additional States," 4 February 2025, nasdaq.com. Moen 2024b: "Moen Enters into Strategic Arrangement with Homeowners Insurance Provider" (Farmers), 19 June 2024, insurance-canada.ca [snippet]. Moen 2024c: "Moen Partners with Amica Insurance to Boost Leak Detection Technology," 24 June 2024, mannpublications.com [snippet].
Competitive and adjacency moves. Ondo 2026a (LeakBot carriers, devices, United States growth). Ondo 2026b: Ondo InsurTech corporate site (Selective 15-state rollout, Co-operative Insurance United States launch), ondoplc.com, read October 2026. Nationwide 2026: Smart home program page (free monitoring device, activation discount, states), nationwide.com, read October 2026. Phyn 2026: Phyn product and partner pages (Protect, Dashboard, premium savings up to 15 percent), phyn.com, read October 2026. Kohler 2026: Smart home product page (Numi, PureWash, Konnect app), kohler.com, read October 2026. Hippo 2026: Smart home page (carrier partners), hippo.com, read October 2026 [snippet]. Nationwide 2024: "Nationwide and Phyn Partner to Offer Advanced Water Damage Protection for Homeowners," 17 December 2024, news.nationwide.com. Coverager 2024: "Amica Partners with Phyn," 28 June 2024, coverager.com [secondary]. Ondo 2024: "New US Contract with Selective Insurance," RNS, 21 February 2024, via share-talk.com [secondary]. Phyn 2021: "Kohler Announces Release of Water Monitoring Products: H2Wise and H2Wise+ Powered by Phyn," phyn.com [snippet]. Kwikset 2026: "Kwikset Launches Aura Reach Smart Lock," 5 January 2026, kwikset.com. Delta 2026: Clarifi 2-Stage Water Filtration System with Beverage Faucet bundle (AVS2-WQ2102-AR), deltafaucet.com, read October 2026. Elkay 2026: Avado single-hole 2-in-1 kitchen faucet with filtered drinking water, AIA 2026 product listing, aiaevents.aia.org, read October 2026 (undated).
Talent signal. Job-posting analysis for the unit was not performed; this family is thin. The July 2025 creation of a Chief Digital and Innovation Officer role and the January 2025 President, Security and Connected Products role are the organizational tells (FBIN 2025d; FBIN 2026e).
News and regulatory. EPA 2026: Per- and Polyfluoroalkyl Substances (PFAS) National Primary Drinking Water Regulation page, last revised 18 May 2026, epa.gov. FBIN 2026q: "Fortune Brands Innovations Appoints Amit Banati as CEO," 12 February 2026, ir.fbin.com [snippet]. FBIN 2026f: "Fortune Brands Announces Governance and Leadership Updates," 16 March 2026, ir.fbin.com. FBIN 2026i: "Fortune Brands Innovations Initiates Strategic Review of Fiberon," 27 May 2026, ir.fbin.com [snippet]. FBIN 2026j: "Message from Interim CEO Dave Barry," 29 May 2026, fbin.com. FBIN 2026k: "Fortune Brands Innovations Appoints Jesse Singh as Chief Executive Officer," 29 June 2026, ir.fbin.com. FBIN 2026p: "Fortune Brands Innovations Names Peter G. Clifford Executive Vice President and Chief Financial Officer," 9 September 2026, ir.fbin.com [snippet]. FBIN 2026d, p. 10 (Supreme Court tariff ruling of 20 February 2026 and tariff risk).
Appendix B. Mathematics
r_{a} = \sqrt[3]{\mathit{Real}_{a} \times \mathit{Worth}_{a} \times \mathit{Win}_{a}}(1)The radius of arena a is the geometric mean of its three lens scores, so a weak lens pulls the spoke toward the center without zeroing it.
S_{i} = \mathit{Real}_{i} \times \mathit{Worth}_{i} \times \mathit{Win}_{i}(2)The composite score of opportunity i multiplies the three ring scores and runs from 8 to 125 for a bet that survives the veto.
s_{i} = \frac{S_{i}}{125}(3)The share of the maximum expresses the composite as a fraction of a perfect score.
\min\left(\mathit{Real}_{i}, \mathit{Worth}_{i}, \mathit{Win}_{i}\right) = 1 \;\Rightarrow\; \text{veto}_{i}(4)Any ring score of 1 vetoes the opportunity, whatever its composite.
G = A_{2030} - \left[ W_{2025}\,(1-d)\,(1 + g_{w})^{4} + C_{2025}\,(1 + g_{c})^{5} \right](5)The gap is the 2030 ambition A_{2030} of USD 3.7 billion less the core trajectory: the Water core W_{2025} of about USD 2.3 billion after a 2026 decline d of 4.5 percent and growth g_{w} of 1 to 2.5 percent a year, plus connected sales C_{2025} of USD 0.3 billion growing g_{c} at 12 to 20 percent a year; G is USD 0.5 to 0.85 billion.
C = \frac{\sum_{i} h_{i} P_{i}}{G}(6)Coverage is the sum of each bet's net-new 2030 prize P_{i} weighted by its probability of success h_{i}, divided by the gap.
References
Sawhney, Mohanbir. 2026. The Growth Radar and the Growth Canvas: A Playbook for Finding and Evaluating Growth Opportunities. SSRN Working Paper, forthcoming.
Growth Radar (Sawhney Enterprises). Scores and prize ranges are illustrative judgments grounded in public evidence as of 12 October 2026.